Mon-Fri 9:00-18:00| Mánesova 48, Praha 2 - Vinohrady| Free initial case assessment via online chat
Client area Book
Commercial law

Tax and social security planning for companies in the Czech Republic

Paying more tax and social security than you need to? Through company tax planning within Czech law, we help you lawfully set up profit distribution, management pay and the use of tax exemptions, so that more capital stays in the company for growth.

4,872 reviews on Google
CZK 50 million professional liability insurance
You know the price in advance
Mlčenlivost podle § 21 zákona o advokacii
At least two lawyers on every case
Typical situations

What business owners come to us with

Eight situations in which companies most often pay more tax and social security than they have to.

Contributions and management pay

  • High contributions on the director's salaryA salary is subject to both social security and health insurance. The right balance between pay and a share of profit can reduce the burden considerably.

    A salary is subject to both social security and health insurance. The right balance between pay and a share of profit can reduce the burden considerably.

  • Profit paid out without a planA dividend instead of part of the pay only makes sense if it is set up correctly. Otherwise you risk an additional tax assessment.

    A dividend instead of part of the pay only makes sense if it is set up correctly. Otherwise you risk an additional tax assessment.

  • Unused tax-advantaged benefitsGood for the company and the employees, but only if backed by internal rules.

    Good for the company and the employees, but only if backed by internal rules.

Exemptions and holding structures

  • Taxed dividends from a subsidiaryIf the statutory conditions are met, they can be tax-exempt. Without a properly set-up holding structure, you pay the tax.

    If the statutory conditions are met, they can be tax-exempt. Without a properly set-up holding structure, you pay the tax.

  • Selling an ownership interest or assets without an exemptionMiss the holding period test and you pay tax you could lawfully have avoided.

    Miss the holding period test and you pay tax you could lawfully have avoided.

Deductible costs and documentation

  • Intra-group services without contractsInvoicing between related companies without evidence of what was supplied is the first target of a tax office audit.

    Invoicing between related companies without evidence of what was supplied is the first target of a tax office audit.

  • Rent for a shareholder's propertyRenting the owner's car or property to the company is a legitimate cost, provided it is backed by a contract and a market price.

    Renting the owner's car or property to the company is a legitimate cost, provided it is backed by a contract and a market price.

  • Licence fees and transfer pricingWithout transfer pricing documentation you risk additional tax and penalties.

    Without transfer pricing documentation you risk additional tax and penalties.

Dealing with something else?Describe your situation to us. We will assess whether and how the tax and social security costs in your company can be lawfully reduced.
Get a no-obligation quote
Scope of the service

What you get with our service

A solution that combines legal certainty with tax and social security efficiency. Depending on the agreed scope, we will provide:

Remuneration of statutory bodies

  • A proposed pay structurethe balance of salary, remuneration for holding office and share of profit

    the balance of salary, remuneration for holding office and share of profit

  • A management agreementor a review of your existing one, with the risks marked

    or a review of your existing one, with the risks marked

  • Documents for the general meetingthe resolution approving the remuneration

    the resolution approving the remuneration

Profit and dividend distribution

  • The legal set-up of profit distributionthe resolution and a check of the conditions under which profit may be paid out

    the resolution and a check of the conditions under which profit may be paid out

  • Advance payments on profit sharesthe procedure and documents for interim payments during the year

    the procedure and documents for interim payments during the year

  • Exempt dividendsa check of whether you meet the statutory conditions for the exemption

    a check of whether you meet the statutory conditions for the exemption

Holding company and corporate group

  • Holding agreementstransfers of ownership interests and the relationship between parent and subsidiary

    transfers of ownership interests and the relationship between parent and subsidiary

  • Intra-group service agreementswith a description of the services that will stand up to an audit

    with a description of the services that will stand up to an audit

  • Checking tax exemptionson the sale of an ownership interest or assets, including the holding period test

    on the sale of an ownership interest or assets, including the holding period test

Our lawyers

Who will handle your case

Two lawyers work on every case, so you always know who you are dealing with, even when one of them is at a hearing.
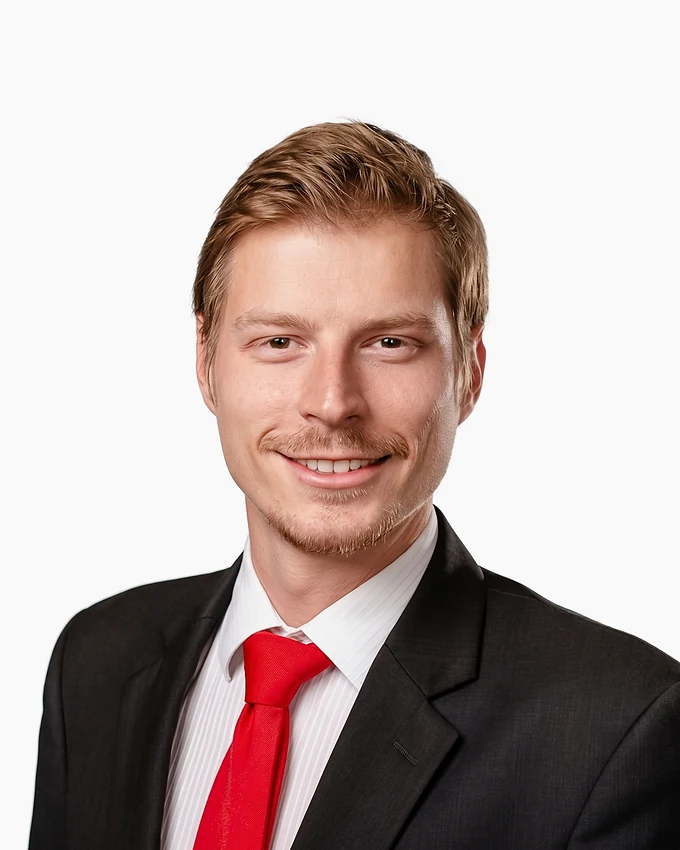
Mgr. Petr Uklein

Mgr. Petr Uklein

Lead attorney · 14 years' experienceCzech Bar reg. no. 19791View profile →
Mgr. Oleksandr Spitsyn

Mgr. Oleksandr Spitsyn

Attorney · 6 years' experienceCzech Bar reg. no. 21443View profile →
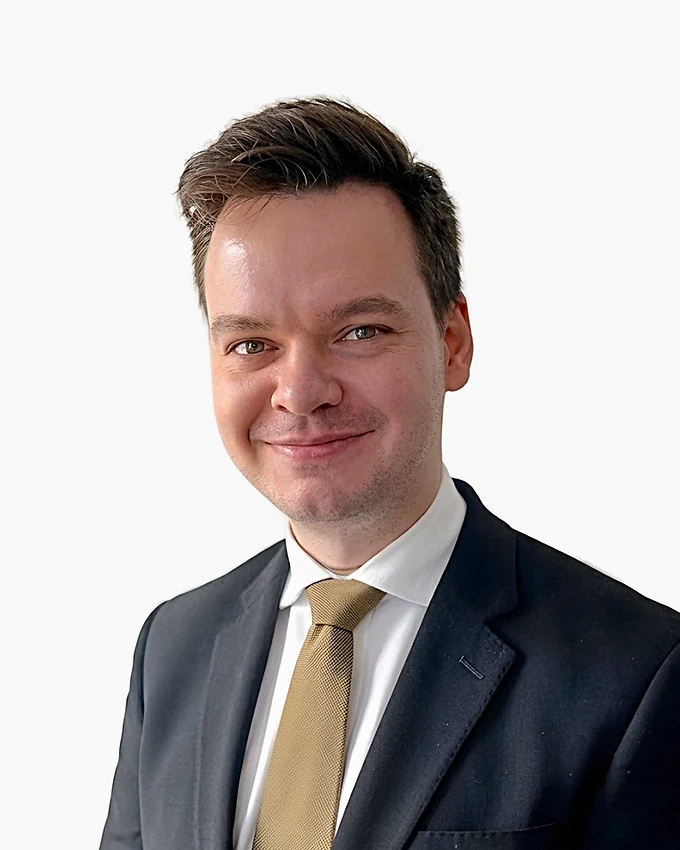
Mgr. David Imre

Mgr. David Imre

Trainee attorney · 4 years' experienceCzech Bar reg. no. 45923View profile →
Worked example

A company compares a profit distribution with the director's pay

First it separates the company's pre-tax profit from profit that has already been taxed.

1
Pre-tax profit

CZK 1,000,000

  • Model pre-tax profit
  • Starting assumption of the modelThe amount is the company's profit before corporate tax, not the director's gross salary or net income. For simplicity, the model assumes that the tax base equals this profit.
2
Corporate tax

21 %

  • Corporate tax rate of 21%
  • Corporate tax calculation21% of CZK 1,000,000 is CZK 210,000. After deducting this tax, CZK 790,000 remains; the following model withholding is calculated from this amount.
3
15% withholding tax

CZK 671,500

  • After the subsequent 15% withholding, the shareholder is left with CZK 671,500
  • Withholding calculation15% of CZK 790,000 is CZK 118,500. After deduction, CZK 671,500 remains. This is the result of one model scenario, not a calculated saving compared with the director's pay.
4
Conditions for payment

Checking the documents before payment

  • Before any payment, the accounting records, the conditions for distributing and paying out profit and the company's cash position are checked.
  • The calculation alone does not determine whether, or when, the full model amount can be paid out.
5
Comparing the options

The same starting cost to the company

  • Together with the accountant or tax adviser, a comparison is prepared with remuneration for holding office at the same starting cost to the company.
  • Current remuneration, the needs of the recipient and the company, and the conditions for each type of payment are taken into account. Without this comparison, the model does not prove that one option is better.
6
Documentation

Follow-up legal steps

  • Depending on the chosen option and the agreed scope, the necessary contracts and the documents for approving or paying out the profit are prepared.
  • The final tax and social security calculations are agreed with the tax adviser.

This is not a client reference. It is a model without exemptions or cross-border effects, not evidence of a client's savings.

Fees

Clear fees. No surprises.

Most work is done for a fixed fee, which we confirm in writing in advance. For more complex matters we agree an hourly rate, always before we start.

Initial assessmentFREEvia online chat
Hourly rateCZK 4,000+ VAT
Fee estimator

How much will it cost to resolve your matter?

Choose an area of law and your situation. The estimator shows you an indicative price before you even contact us.

Estimate your fee

Prices are indicative and exclude VAT. Unless expressly agreed otherwise, court, administrative and notarial fees, insurance premiums and external expert reports are not included. We will send you the price for your matter in writing before we start work.

Practical checklist · 7 pointsCo si připravit pro posouzení optimalizaceOpen checklistClose checklist
Prepare the latest financial statements
Provide the management agreements
Summarize how pay has been structured so far
Provide the profit distribution resolutions
Describe the links between the companies in the group
List planned investments and payouts
Get the view of your accountant or tax adviser
Reviews

What our clients say

Excellent 4.8 72 reviews on GoogleWrite a review
Tud Ars20 November 2025 · Google
★★★★★
They helped me with very good advice on how to run my projects. The consultation was scheduled very fast and talk was very professional.
Mark H13 October 2025 · Google
★★★★★
Very efficient and professional, the problem is with the czech police but the lawyers are excellent would recommend
V Vaso20 June 2025 · Google
★★★★★
I highly recommend this law firm. Together we dealt with a criminal matter in which I was the injured party. Thanks to their human approach and willingness… (translated from Czech)
Anna Šípová14 June 2025 · Google
★★★★★
The firm handled my employment dispute and I was very satisfied. In the end the whole matter was settled out of court… (translated from Czech)
Frequently asked questions

Business owners' FAQs

Didn't find your answer? Message us in the chat. The initial case assessment is free.

Ask in the chat
Can the tax burden be lawfully reduced for a managing director who is also a shareholder?

Yes. Depending on the situation, remuneration for holding office, profit shares and suitable benefits can be compared. Each component has its own conditions for approval, payment and taxation. The proposal must reflect reality, and the tax calculations need to be agreed with a tax adviser.

Can you also help with cross-border invoicing and AML documents for the bank?

Depending on the agreed scope, we prepare documents on intra-group relationships, evidence of what was supplied and explanations of transactions for the bank. We cannot guarantee that the bank will not carry out a check, ask for further documents or hold a payment.

What percentage can we realistically save with an optimized structure?

Without an analysis of income, costs, profit distribution and personal circumstances, no reliable percentage can be given. First we compare the options at the same starting cost to the company.

Is there a risk the tax office will audit us?

A tax audit cannot be ruled out even with a lawful set-up. Proper contracts, real transactions and solid documentation help prove the approach was correct, but they are no guarantee that an audit will not come.

What is an exempt benefit?

It is income that the law exempts from tax under certain conditions. For benefits or contributions, what matters is the type of benefit, the recipient, the statutory limit and whether the other conditions are met; one limit cannot be applied to every case.

Is social security payable on dividends too?

No social security contributions are due on an ordinary profit share paid to a shareholder of a limited liability company (s.r.o.) as income from capital. A payment that is in fact remuneration for work or for holding office must be assessed differently.

Which is better: a higher salary or higher dividends?

There is no universal answer. Pay and profit shares have different conditions, costs and effects on contributions and social security entitlements. We compare them according to the needs of the company and the recipient, not just one tax rate.

Want to lawfully reduce tax and social security in your company?We review the director's pay, profit and dividend distribution and the holding structure. We propose a solution that the law expressly allows and prepare the documents it needs.Mon-Fri 9:00-18:00 · Free initial case assessment
Get a no-obligation quote
Our blog

Articles on commercial law

Commercial law13 June 2026 · 6 min read
Customs office inspections

The customs office checks many obligations and an inspection is stressful for many businesses, but for anyone who knows how it works, what ...

Mgr. Petr Uklein · Lead attorneyRead
Get in touch

What happens next

  1. 1We assign your matter to a specialistBased on the area you choose in your enquiry.
  2. 2We get back to you within 24 hoursOn working days, by phone or email.
  3. 3You receive a plan and a priceIn writing, before any work begins.
In a hurry? Message us in the online chat and we will reply straight away.

You can attach a contract or photos: up to 5 files, 10 MB each.

Mon-Fri 9:00-18:00 · we reply promptly